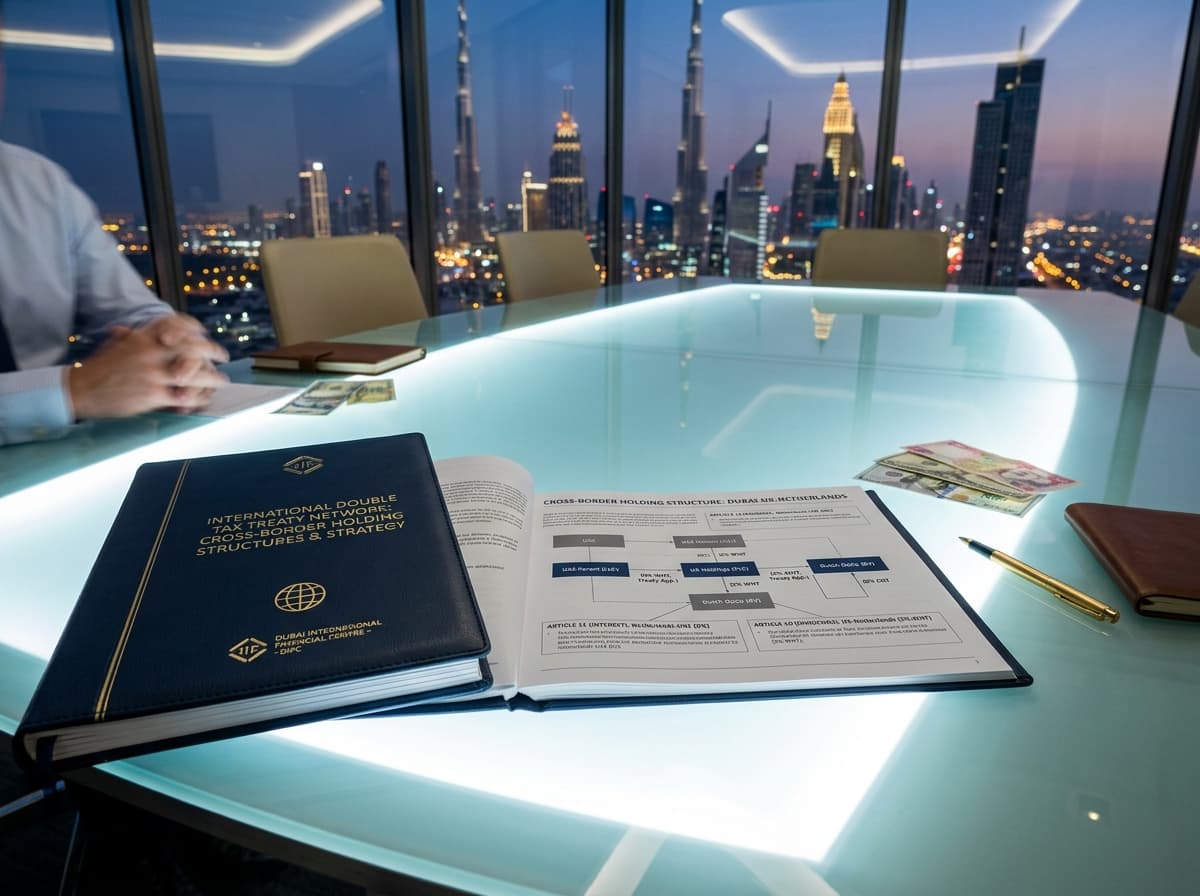
We assess cross-border payments such as interest, royalties, service fees and dividends against the relevant source-country rules and treaty provisions. The work considers eligibility, documentation and contractual tax clauses; it does not assume the same treatment in every country.
We assess cross-border payments such as interest, royalties, service fees and dividends against the relevant source-country rules and treaty provisions. The work considers eligibility, documentation and contractual tax clauses; it does not assume the same treatment in every country.
02 / In practice
From your facts to a clear approach
We take each payment flow and determine its character, the domestic withholding treatment, the treaty rate potentially available and the documentation needed to claim it - residence certificates, beneficial-ownership support, contract wording. The output is a payment matrix your finance team can apply at the moment of remittance, not a theory that arrives after the transfer.
03 / The outcome
What you receive
A withholding-tax matrix by payment type and country, with the documentation checklist for each flow.