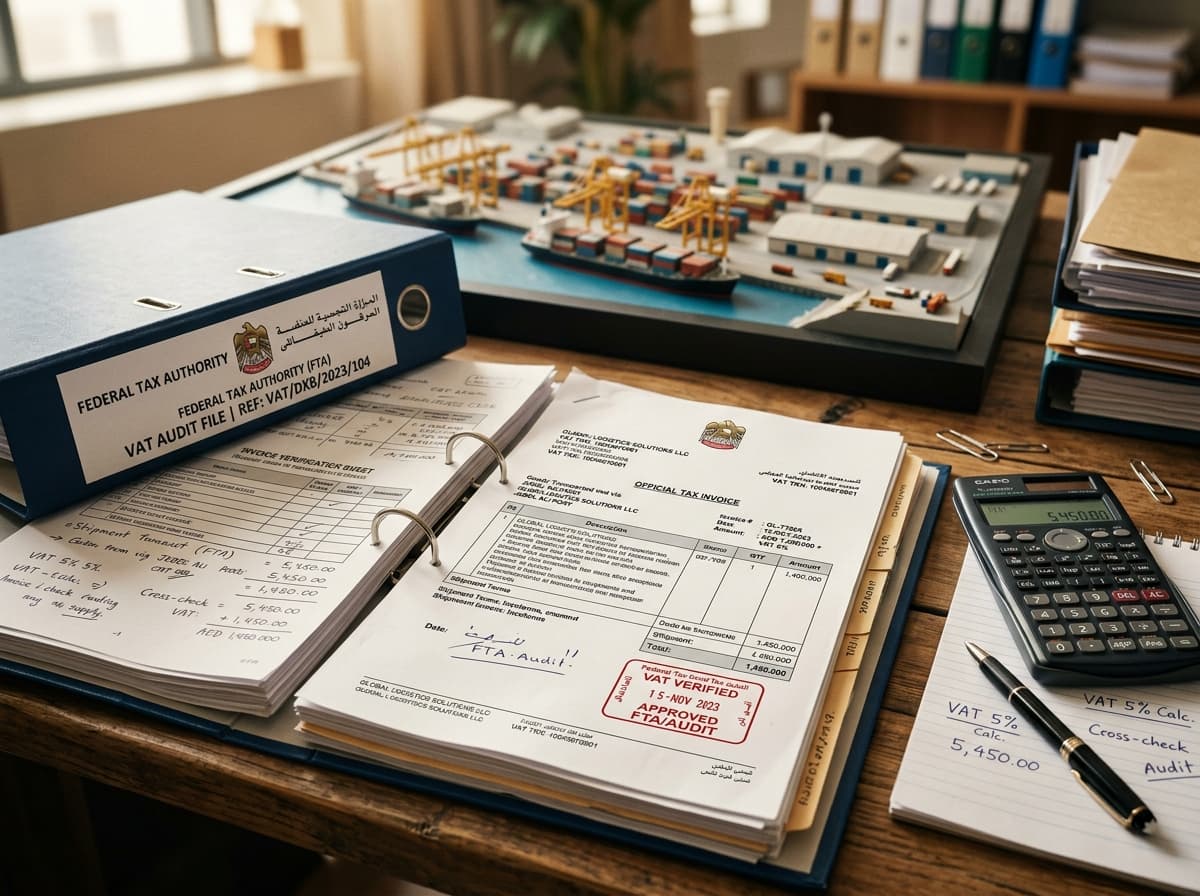
We review recoverability of input tax, allocation methods and supporting documents. For businesses with mixed activities, we assess the basis used to separate recoverable and non-recoverable amounts and identify whether further review or an application is needed.
We review recoverability of input tax, allocation methods and supporting documents. For businesses with mixed activities, we assess the basis used to separate recoverable and non-recoverable amounts and identify whether further review or an application is needed.
02 / In practice
From your facts to a clear approach
We test recovery claims against the use of each cost, verify the documents that support deduction, and - for mixed businesses - examine whether the apportionment method actually reflects how costs are consumed. Where the standard method distorts the outcome, we quantify the difference and assess the case for an alternative approach.
03 / The outcome
What you receive
A recovery analysis with documentation findings and, where relevant, an apportionment-method assessment.